Excerpts from UOB KH
Analysts: John Cheong & Clement Ho
| Pure Green Investments Play After Sale Of M&S Business Sunpower is selling its M&S business at an attractive valuation, which will result in a special dividend distribution of S$0.2359/share.
The GI segment has superior cash flow generation capability relative to the M&S segment, with 30-year operating concessions providing long-term revenue visibility. Maintain BUY with an 18% higher target price of S$1.10. |
||||
WHAT’S NEW
• Disposal of M&S business. Sunpower Group (Sunpower) is selling its manufacturing & services (M&S) business for Rmb2.29b.
The manufacturing-based business will be sold to a special purpose vehicle that will be owned by a consortium of China funds (64%), the group’s two largest shareholders, Guo Hong Xin and Ma Ming, and certain employees of the M&S segment (36%).
The sale price translates to 12.2x 2019 PE and represents close to 50% of Sunpower’s current market cap.
We deem the deal as attractive, at a valuation more than twice the 5-7x ascribed by the street.
Furthermore, the disposal of the order-driven M&S business will leave investors with the remaining power-producing-related green investments (GI) business, which offers greater revenue visibility and certainty.
• Special dividend proposed post-sale. Sunpower intends to pay out a special dividend amounting to Rmb1.34b, or S$0.2359/share, split into two tranches.
After which, the remaining amount will be used to repay payables due from the GI business to the M&S business of Rmb 130m, as well as Rmb551m earmarked for existing GI projects and working capital.
• Redirects strategic focus on successful GI business. The GI business has significantly more potential to deliver long-term sustainable benefits to the group due to its proven capacity to deliver sizeable recurring income and cash flow.
Unlike M&S which is an inherently cyclical, order book-driven business that requires high working capital, GI has the ability to generate recurring cash flow that is sustainable over the long term due to:
| a) 30- year operating concession rights; b) Sunpower’s exclusive supplier status with a captive customer base; and c) mission-critical, non-discretionary products such as steam and heating. |
STOCK IMPACT
• Sunpower to become a fast-growing power-producer. Currently, Sunpower has nine plants in operation and two under construction. 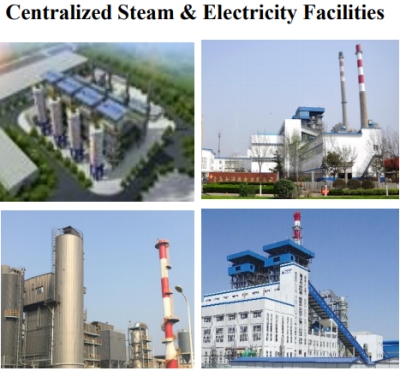 Sunpower’s GI business supplies industrial steam to a wide range of industries.With four of the plants acquired through M&A - almost half of its existing portfolio, M&A opportunities have been abundant and the proposed disposal would put the group in good position to source for more M&A targets.
9M20 financials reflected strong contributions from operational GI plants and the continued ramp-up of existing projects.
We expect earnings for the rest of 2020 and beyond to be driven by:
| a) full-year contributions from newly-acquired GI plants; b) additional contributions from Phase 2 of the Shantou Project and the new Xintai Zhengda plant; c) continuous acquisition of new customers following mandatory closures of “small dirty boilers” and/or mandatory relocations into industrial parks; and d) organic growth of existing customers and industrial parks served by the group’s GI plants. |
• China’s economic recovery provides favourable tailwinds. According to the National Bureau of Statistics, China’s 3Q20 GDP grew 4.9% yoy and the economy is on track for a full recovery.
Furthermore, the International Monetary Fund and Oxford Economics have increased their GDP growth forecasts for China to 1.9-2% yoy (1-2% yoy previously), with China being one of the few countries to be given positive growth forecasts.
With the COVID19 pandemic relatively under control in China, we believe Sunpower is in a favourable position to benefit from the full resumption of economic activity in China and will post strong results for 4Q20.
EARNINGS REVISION/RISK  John Cheong, analyst.• We maintain our revenue and EPS forecasts. VALUATION/RECOMMENDATION • Maintain BUY with a higher target price of S$1.10 (from S$0.92) after incorporating the net proceeds of Rmb2,021m from the disposal of the M&S business. Our target price implies an attractive 11.4x 2021F PE. SHARE PRICE CATALYST • Faster-than-expected ramp-up of GI projects. • More EPS-accretive acquisitions |
Full report here.


