• Why has the Singapore market fallen? Part of the weakness has followed the US market, where AI stocks have been hit by concerns over high interest rates and expensive financing. • Higher borrowing costs make it more expensive to fund the huge investments needed for AI infrastructure. They also put pressure on highly leveraged investors, forcing some to cut their positions. • When heavily owned AI stocks start falling, this selling snowballs. Funds may be forced to reduce exposure, meet margin requirements or simply lower risk. • The good news is that a leverage-driven selloff can reverse fairly quickly once the forced selling is over. If you are looking for oversold stocks, read the excerpts from UOB Kay Hian’s report below.... |
Excerpts from UOB Kay Hian report
Analysts: Singapore Research Team
• Our Oct 26 Alpha Picks underperformed the FSSTI by 2.2ppt, 1.4ppt and 0.4ppt on a price-weighted, market cap-weighted and equal-weighted basis respectively.
• One new addition; two removals. We add Yangzijiang Shipbuilding (YZJSGD SP) for its strong contract win momentum, with large vessel delivery slots fully booked through 1H30, and earnings expansion from its Hongyuan yard from 2027. We remove OCBC (OCBC SP) as banks are high beta and more susceptible to swings caused by geopolitical uncertainties. |
| Yangzijiang Shipbuilding – BUY (Roy Chen) |
• Strong order wins extending performance visibility into 2030. Management sounded increasingly confident of meeting or exceeding its US$4.5b 2026 contract-win target, with US$1.96b secured in 7M26.
We understand that Yangzijiang Shipbuilding’s (YZJ) large-vessel delivery slots have been fully booked through 1H30, and believe its healthy enquiry pipelines across containerships, oil tankers and bulk carriers should support further order wins.
• 2H26 and 2027 earnings expansion underpinned by strong margins and capacity expansion. We expect YZJ’s 2H26 margins to remain steady vs 1H26, supported by a similar project mix hoh and good-margin large containership contracts.
The Hongyuan yard is on track to commence operations in early-27 and could contribute about 20% of 2027 revenue, expanding YZJ’s earnings potential to a new level.
• Maintain BUY on YZJ with a target price of S$5.90. Our target price is based on 10.1x 2028F PE, or +2SD above YZJ’s historical mean, reflecting YZJ’s good earnings visibility that extends into 1H30.
YZJ is trading at about 8x 2027F PE, representing an approximate 20% discount vs peers averaging near 10x.
YZJ offers an attractive 5.5-6.4% dividend yield in 2026-28, supported by a strong net cash position.
| Oiltek International – BUY (Tang Kai Jie) |
• Landmark RM1.4b SAF project secures growth visibility. Oiltek International’s (Oiltek) EPCC contract for a large-scale sustainable aviation fuel (SAF) facility in Sabah provides strong earnings visibility and positions the group at the forefront of the renewable fuels value chain.
The deal is currently in progress for land purchase, licensing and funding drawdown, with the land offer letter expected by end-26.
• Healthy orderbook and strong balance sheet supporting 2H26. The group’s current orderbook remains healthy at approximately RM258.7m.
Balance sheet also continues to be strong and resilient with no bank borrowings and healthy cash and bank balances of RM95.1m, representing 92.2% of net assets.
• Favourable refinery and renewable energy outlook. Oiltek expects sustained growth in its edible & non-edible oil refinery segment, driven by rising global fats and oils demand.
Renewable energy tailwinds remain strong, supported by growing biodiesel and SAF demand, with Oiltek pursuing several billion-ringgit worth of SAF opportunities.
• Growth strategy focused on asset-light expansion. Oiltek is expanding into new markets and larger-scale projects while building recurring income through low-capex JVs. The company is also exploring new growth avenues.
• Ongoing corporate actions. Management is also advancing a potential Bursa secondary listing and the spinoff of its JV.
• Maintain BUY with a target price of S$2.78, based on 28x 2027F PE (1SD above historical PE mean).
We believe a strong contract win and delivery of better earnings could continue to support a re-rating, while Oiltek’s assetlight model, high ROE (>30%) and healthy margins support earnings growth.
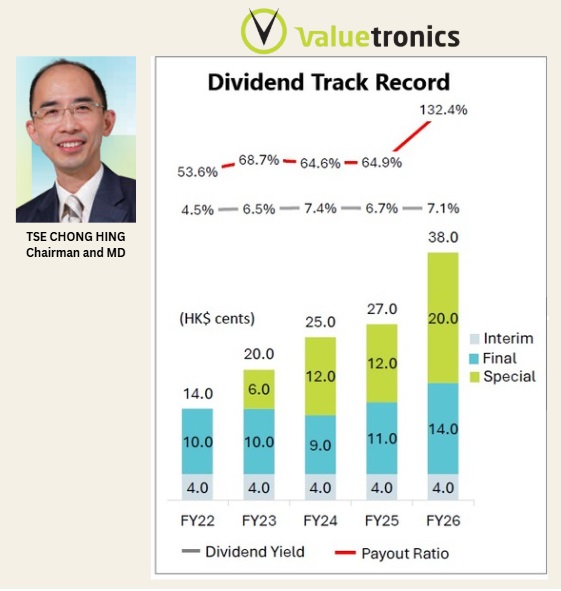
• FY26 results: Record gross margin despite one-off impairment. FY26 revenue was HK$1.66b (-4% yoy), in line with estimates. |
 See also: This Multi-Continent Business Delivers Record Revenue, Record Profit, Record Dividends, Record Stock Price |


