|
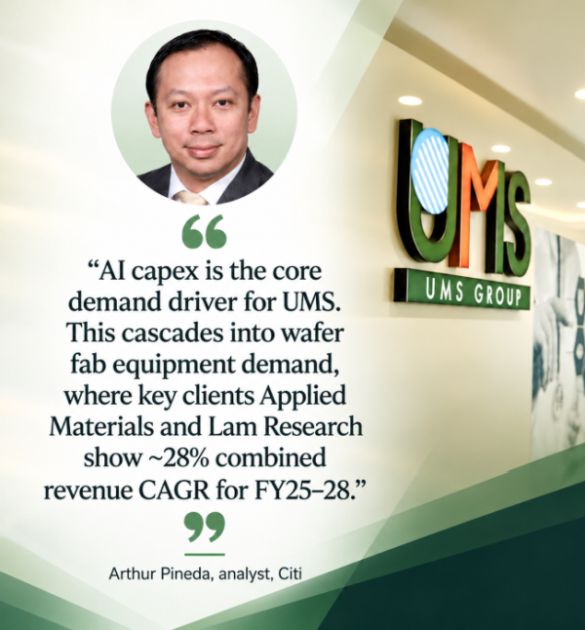
UMS Integration has gained a big-name research house. Citi Research analyst Arthur Pineda initiated coverage on 24 Sept with a “Buy/High Risk” rating and S$3.43 target price, describing UMS as a precision-engineering beneficiary of the AI-driven semiconductor “super-cycle”. Citi is aggressive in its FY2027-2028 forecasts of revenue and profit as compared with DBS and UOB Kay Hian.
|
| Attractive discount |
Interestingly, there is almost no disagreement about FY2026.
But Citi's aggressive forecasts after FY2026 contrast strikingly with UOBKH and DBS:
|
Revenue |
|||
|
S$m |
FY26F |
FY27F |
FY28F |
|
Citi |
330 |
436 |
577 |
|
DBS |
331 |
395 |
466 |
|
UOBKH |
326 |
362 |
402 |
Citi's FY28 revenue forecast is about 24% higher than DBS's and 44% higher than UOBKH's.
That's a very big difference.
However, despite having by far the highest earnings forecast, Citi does not have the highest target price.
|
Net Profit |
||||
|
S$m |
FY26F |
FY27F |
FY28F |
TP |
|
Citi |
68 |
96 |
136 |
S$3.43 |
|
DBS |
70.0 |
84.7 |
102 |
S$3.62 |
|
UOBKH |
72.0 |
84.4 |
97.0 |
S$3.27 |
Citi values UMS using a hybrid approach: 22 times FY2028 earnings gives S$3.38, while its discounted cash-flow valuation gives S$3.48.
Averaging the two produces its S$3.43 target.
UOBKH analyst John Cheong, meanwhile, uses a much richer 30 times FY2028 EPS to arrive at S$3.27.
He actually reduced his valuation multiple from 37.5 times, arguing that UMS is moving into a later stage of the semiconductor earnings cycle.
DBS analyst Lee Keng Ling is more generous still, applying 38 times FY2027 earnings to derive its S$3.62 target — the highest of the three.
UMS closed at $2.63 yesterday.
| Curious situation |
So we have a curious situation:
-- Citi has the most bullish earnings forecasts but the lowest valuation multiple.
-- DBS has more moderate forecasts but the highest target price because it applies the richest P/E.
To Citi, the main drivers will be volume growth and economies of scale.
Citi expects net profit to rise from S$42 million in FY2025 to S$136 million in FY2028, with ROE soaring from 9.8% to 27.2%.
DBS and UOB KH also see considerable operating leverage but are less aggressive in their profit forecasts.
All three houses broadly agree that FY2026 is going to be strong. The real debate is what comes next. Does UMS end up near UOBKH's moderate S$402 million revenue by FY2028? Or does it reach DBS's S$466 million?
|
 For earlier story, see: AI Wave lifts UMS' profit -- and Analysts Up Target Prices by 70-120% |


