|
ISDN Holdings’ 9M2026 results were already strong, but management’s latest presentation provided an even more interesting datapoint: business momentum apparently strengthened further in October. For 9M2026,
CGS International analyst William Tng said the results represented a “material outperformance”. As a result, CGS raised its FY26, FY27 and FY28 EPS forecasts by 33.0%, 29.9% and 19.6%, respectively. |
|||||
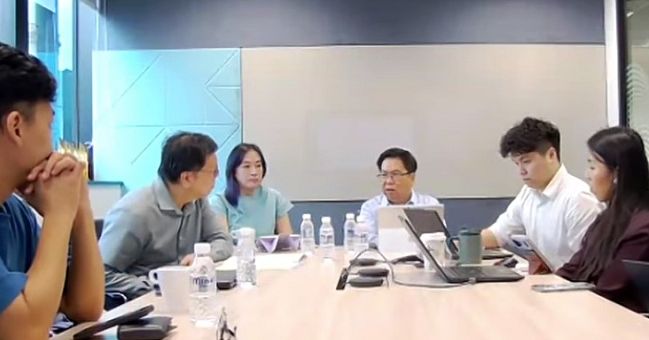 ISDN managing director CK Teo and CFO Christine Ho at the 3Q2026 hybrid briefing: "“ISDN delivered a strong performance in the first nine months of 2026, with record revenue and a significant improvement in profitability."
| Strong order book |
Management’s comments suggest even CGS’s revised FY26 number may not be especially aggressive.
Managing director Teo Cher Koon said October was strong while the order book continued to grow, with some orders flowing into 2027.
When an investor suggested FY26 profit could reach S$28 million to S$30 million, however, Teo declined to endorse the estimate: “I don't want to speculate.”
There is an important qualification.
ISDN’s normal delivery lead time had been around three months, but Teo said it is getting longer because of supply-chain constraints.
Thus, some of the order-book growth reflects longer fulfilment times rather than pure demand growth.
Still, management expects 1H2027 to remain strong although Teo remains cautious about 2H2027 because semiconductors are cyclical.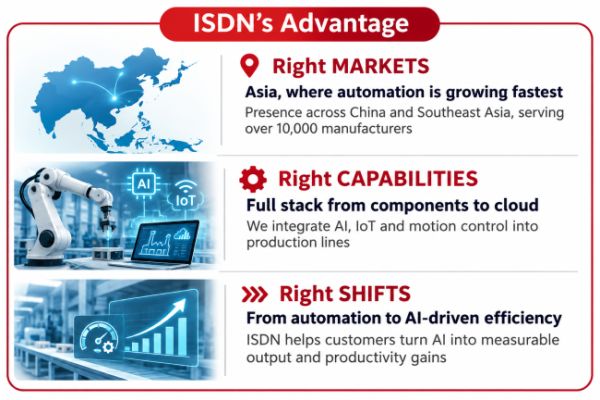
| Hydropower catalyst approaching |
The two new mini-hydropower plants also are close to commercial operation.
Asked what remained to be done, Teo said mainly “administrative nitty-gritty stuff”.
Asked when the full S$14 million annual recurring net cash income from the enlarged five-plant portfolio should kick in, his answer: “Next year.”
(This is group/project-level recurring net cash income, not fully attributable to ISDN shareholders).
CGS sees hydropower as one possible re-rating catalyst if its profit contribution exceeds expectations.
Other catalysts include stronger China growth and a stronger semiconductor recovery.
Meanwhile, management disclosed a potentially sizeable renewable-energy pipeline: ISDN is discussing several solar projects totalling roughly 100MW to 200MW, although these remain preliminary.
Source: CGS International Research, Company Reports The reason is valuation. CGS previously valued ISDN at around 21 times earnings. CGS forecasts ISDN trading at just 8.6 times FY26 earnings and 7.8 times FY27 earnings at S$0.51. |
 See the 3Q update here. See also: ISDN: Its 707% Profit Jump Isn’t the Real Story. Look Instead at Its Automation Momentum and Hydropower Cash-Flow Growth |


