|
Centurion Accommodation REIT (CAREIT) is turning additional dormitory beds into rental income, helping its results exceed the forecasts made at its IPO. DBS Group Research sees more benefits ahead for the REIT that listed on the SGX in Sept 2025.
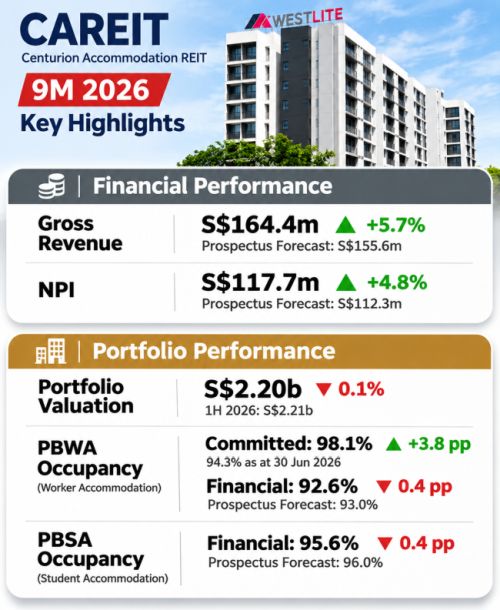
For 9M2026, CAREIT reported revenue of S$164.4 million and net property income (NPI) of S$117.7 million, exceeding prospectus forecasts by 5.7% and 4.8%, respectively. 3Q revenue and NPI reached S$55.5 million and S$39.3 million, respectively, beating prospectus forecasts by 6.9% and 5.7%. |
||||
| Singapore drives the performance |
Higher rents, improved occupancy at selected properties and expanded capacity supported the Singapore purpose-built worker-accommodation (PBWA) portfolio.
Committed occupancy rose to 98.1% at Sept-end, from 94.3% at June-end.
Westlite Toh Guan reached 99.7%, while Westlite Mandai achieved 95.1%.
These commitments include some tenancies that have yet to commence.
Wrote DBS:
“We remain positive on CAREIT's outlook, underpinned by resilient demand for PBWA and the progressive contribution from newly expanded capacity.”
Expanded capacity at Toh Guan and Mandai contributed S$2.3 million in additional revenue during the nine months. Management expects approximately S$3.5 million for the full year.
Part of the outperformance came from additional bed capacity that was not factored into the IPO forecasts.
Toh Guan’s retained 664 beds were excluded from the prospectus forecast, while licensing for Mandai’s expanded capacity arrived in May, two months earlier than originally forecast.
This helped bring rental contributions forward during the year.
DBS said of the ongoing leasing progress:
“This should support stronger earnings contributions into FY27, alongside the full-year impact of the expanded capacity at Westlite Toh Guan and Mandai.”
| UK softness needs perspective |
The UK student-accommodation portfolio faced softer rents, temporary bed reductions for upgrading works and higher marketing expenses.
Financial occupancy was 94.7% for the nine months, compared with 99.1% in the first half.
However, the reporting convention excludes July and August.
CAREIT says occupancy would have been 98.9% if the actual summer holiday period, typically mid-July to mid-September, were excluded instead.
The alternative calculation suggests that seasonality contributed significantly to the reported decline, although softer rental rates and higher marketing expenses remain concerns.
Australia’s student-accommodation occupancy remained high at 97.8%.
Across the portfolio, the NPI margin of 71.6% was slightly below the forecast 72.2%, indicating that stronger revenue did not translate fully into property income.
Favourable exchange-rate movements involving the British pound and Australian dollar also contributed to the results.
| Financing |
Gearing stood at 30.7%, with interest coverage of 5.66 times.
No drawn debt matures before FY2028, providing breathing room for management.
Financing cost was 3.65%, below the prospectus assumption of 4.07%, although slightly above June’s 3.60%.
Including amortisation of upfront and other fees, the cost was 3.92%.
Further expansion is planned. However, some existing capacity is scheduled to be phased out: Toh Guan faces a 1,270-bed reduction in 2029. Part of the expansion programme therefore helps preserve the earnings base. DBS cited forecast distribution yields of 7.2%–8.2% for FY2027–28 based on a $1.04 stock price. |
 See the Powerpoint deck here. See also: CENTURION REIT: Beats IPO prospectus forecasts. The interesting story is what comes next |


