|
Geo Energy’s earnings recovery is gathering pace, with its new MBJ road-and-jetty infrastructure beginning to contribute—and October’s operating figures strongly suggesting greater benefits ahead. Executive chairman and CEO Charles Antonny Melati was upbeat:
|
| Higher prices, higher costs |
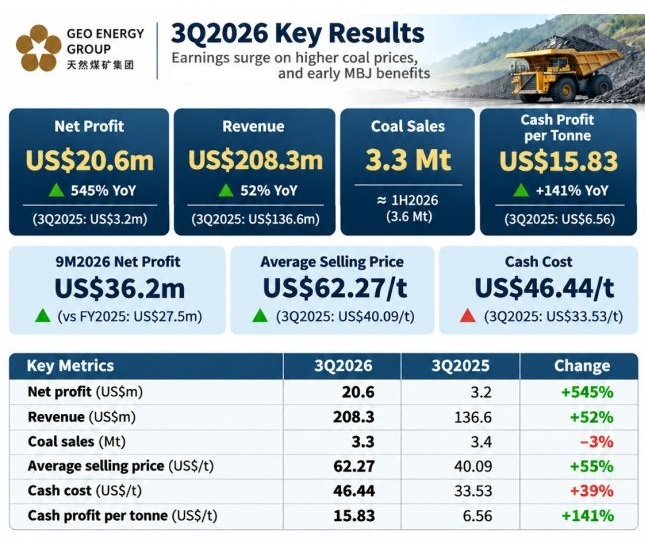
Geo sold 3.3 million tonnes of coal during the quarter, almost matching the 3.6 million tonnes sold throughout 1H.
However, sales were slightly below the 3.4 million tonnes recorded a year earlier.
The year-on-year improvement was therefore principally a pricing story: Average selling price climbed to US$62.27 per tonne from US$40.09.
Cash costs also rose, however, reaching US$46.44 per tonne against US$33.53 previously -- mainly due to “higher fuel prices, higher strip ratios as well as higher royalty costs due to higher selling prices”.
Nevertheless, cash profit improved substantially to US$15.83 per tonne, from US$6.56.
Tax was another restraint. Geo’s effective tax rate reached 39%, leaving net profit of US$20.6 million from pretax profit of US$33.9 million.
| MBJ’s contribution is only beginning |
MBJ’s early benefits were tangible but limited.
Approximately 300,000 tonnes passed through the infrastructure during 3Q—roughly 9% of group coal sales. The company reported cash-cost savings of US$11 per tonne transported through MBJ.
Using those figures, the savings amounted to US$3.3 million.
October provides a more encouraging indication of what could follow.
Geo sold around 1.4 million tonnes that month. Crucially, MBJ handled 350,000 tonnes in October alone.
Roughly one-quarter of October’s sales therefore passed through MBJ, compared with about one-tenth in 3Q.
Melati said:
Charles Melati“We expect these benefits to build up as a greater proportion of TRA’s coal volumes is transported through MBJ, supported by the commencement of double-trailer haulage in October 2026.”
The double-trailer configuration carries two 70-tonne trailers, supporting further logistics efficiencies as more coal from the Triaryani mine moves through MBJ.
| What matters next |
The coal-price backdrop remained supportive: ICI4 stood at US$79.22 per tonne on 6 November, versus a 3Q average of US$67.75. These are benchmark prices, not Geo’s realised selling prices.
Management expects further operational improvement in 4Q and substantially higher full-year profitability, assuming coal prices remain around US$78 per tonne and TRA volumes increase as planned.
Shareholders will receive a 0.25 Singapore cent quarterly dividend, bringing nine-month dividends to 0.45 cent. Management will assess full-year performance before declaring the final dividend.
Melati said that as earnings and cash flow generation strengthen, Geo would consider increased dividends and share buybacks.
On 6 Nov 2026, at the 9th China International Import Expo in Shanghai, the group signed two non-binding agreements with entities within major Chinese state-owned enterprise groups. The agreements deal with developing its TRA mine and MBJ infrastructure while exploring new avenues for growth. 1. Potential expansion of TRA’s northern mining area to 12.5 million tonnes a yearTRA signed a framework agreement with CCCC First Harbor and NORINCO International to explore mining services, intelligent equipment, digital dispatch systems and possible financing. This could provide the mining capability needed to complement MBJ’s logistics infrastructure and expand output. 2. CHN Energy could become both a strategic investor and a coal buyerA MOU with CHN Energy International explores investment involving TRA and/or MBJ, alongside a potential coal-purchase arrangement of up to 2 million tonnes in 2027. |
 See the results announcement here. See also: GEO ENERGY: Backs Bullish Profit Guidance With Record Buyback—At A Higher Price |


