|
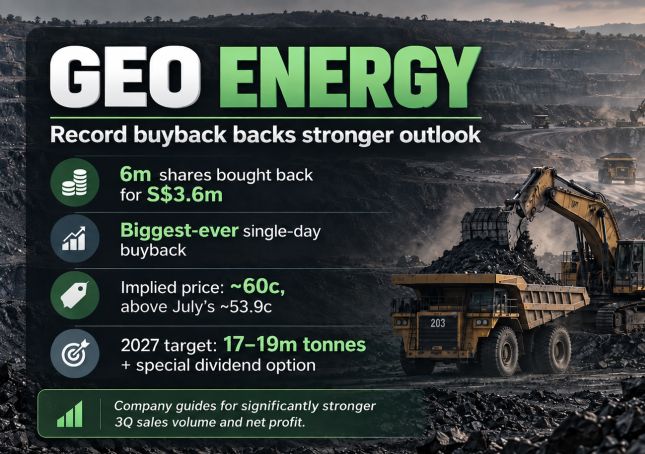
It’s one thing to say your shares are cheap. Geo Energy has put money behind that view—with its biggest-ever single-day buyback. On 5 Oct, the company acquired 6 million shares for S$3.6 million—slightly more shares than the approximately 5.8 million bought back earlier this year. The size of the purchase is striking. So is the price. The rounded figures imply an average of about 60 cents a share, roughly 11% above July’s estimated buyback average of 53.9 cents.
|
| Backing its profit guidance |
On 28 Sept, Geo said it expected sales volume and net profit for 3Q2026 to increase significantly against not just 3Q2025, but also each of the first two quarters of 2026.
There are reasons for that optimism.
The ICI4 coal benchmark averaged US$76 a tonne in September, approximately 31% above its first-half average of US$58.13.
Meanwhile, Geo’s operational MBJ road-and-jetty infrastructure is expected to save its TRA mine more than US$10 a tonne in logistics costs while enabling higher production.
Geo says it is still finalising an agreement for ResInvest to invest in a substantial stake in MBJ.
Geo expects operational improvements to continue into 4Q, provided coal prices hold and TRA volumes increase as planned. In the 5 Oct release, Geo said:
With 3Q2026 earnings expected to rise significantly and MBJ’s value proposition, the Board believes that the Group is entering one of the strongest growth phases in its history.
| A slightly broader 2027 target |
Geo now targets total coal production and sales of 17–19 million tonnes in 2027, subject to final mining plans and Indonesian mining-plan approvals.
NextInsight’s August coverage had reported a possible 17–18 million tonnes of group production.
The new range therefore lifts the upper end by one million tonnes while leaving the lower end unchanged. This is a modest broadening of the ambition, not a dramatic forecast upgrade.
Geo describes the 2027 target as an increase of over 50% from 2026 -- the growth opportunity is substantial.
The board has also explicitly included special dividends among its future capital-allocation options, alongside regular quarterly dividends and active buybacks.
Around mid-Nov, watch for the 3Q results and the subsequent full-year results to see to what extent Geo has turned stronger coal prices, rising volumes and lower logistics costs into higher profits and cash flow and shareholder returns. |
 See also: GEO ENERGY: MBJ Is Up and Running — Will A ResInvest Deal Change How the Market Values Geo? |


