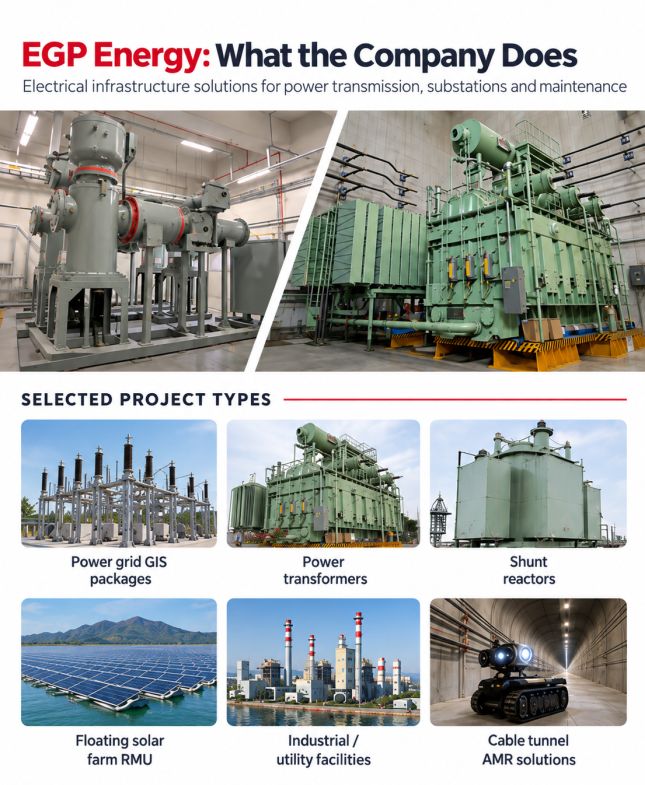
• Its work includes high-voltage substations, switchgear, transformers and other equipment needed to transmit and distribute electricity. • The investment case is fairly simple: EGP operates in a specialised field with high barriers to entry, has a very large order book, requires relatively little capital to grow, and has a maintenance business that can provide recurring, high-margin income. The main risk is that a very large part of its business comes from one major customer -- SP PowerGrid. • EGP has been in this business for more than 30 years and has completed over 90 projects. It is qualified to undertake large electrical engineering projects without a contract-value limit. Only a small number of companies in Singapore have this qualification and the experience needed to handle major high-voltage power projects. • OCBC Research has just initiated coverage. Read excerpts of its report below ..... |
Excerpts from OCBC Research report
Analyst: Heidi Mo
Initiation: EGP Energy Corporation Limited (EGX SP)
• Market-leading T&D contractor and one of only 16 firms in Singapore holding the BCA SY04 L6 Unlimited certification with a 37.5% EHV/HV switchgear market share
• Robust SGD296.2m order book (4.8x FY25 revenue) is expected to drive an average annual growth of 36% from |
|||||
| Market leadership backed by regulatory moat |
EGP commands 37.5% of Singapore’s EHV/HV switchgear market, supported by its BCA SY04 L6 Unlimited certification (only 16 firms in Singapore hold this apex license for T&D EPC contracts).
Its 30-year track record with zero reportable safety incidents and deep technical expertise in multi-OEM integration differentiate it from generalist
competitors and provide pricing power.
Robust orderbook locks in multi-year revenue pipeline. EGP’s SGD296.2m order book (as of 13 Aug 2026) represents 4.8x FY25 revenue, of which we project that 65% of these contracts will be recognised from 2H26 to 2H28.
Its KUC provides non-discretionary, legislatively mandated T&D capex visibility through 2030, underpinned by Singapore’s Energy 2050 target of 6GW
low-carbon electricity imports and data centre electrification (700MW+ new capacity approved).
The order book excludes recent contract wins (SGD8.8m from 13 Aug 26) which validate continued customer confidence.
| Superior unit economics drive profit growth |
We forecast EGP to deliver strong profitability in FY26E with 24.4% core EBITDA margin versus peer average of 11.5%, while capex should be minimal at around 2% of revenue.
The asset-light, non-manufacturing model avoids heavy capex and working capital drag typical of manufacturing competitors.
M&S contracts generate 50% gross margin (FY23-25 average), on an installed base of over 4,010 Mega Volt-Ampere (MVA), providing recurring revenue anchored to its KUC’s 7,000+ substations and creating a transition toward a service-led, higher-margin business model.
Its negative working capital cycle also enables self-funding operations and rapid cash conversion.
Demand tailwinds drive TAM expansion. Singapore’s Power Transmission and Distribution System (PTDS) market grew at a compounded annual growth rate (CAGR) of 56% from SGD585m in 2022 to SGD2.24b in 2025 and is expected to reach SGD2.79b by 2030 (5% CAGR).
Growth is driven by solar power purchase agreements (SPPA), green hydrogen import infrastructure, undersea HVDC cables (6GW low-carbon electricity imports by 2035), data centre expansion, semiconductor manufacturing capex, EV charging infrastructure, and equipment replacement cycles (installed in 1980s-2000s).
Regional opportunities are also materializing. Malaysia's TNB RP4 framework allocates MYR14.3b (SGD4.8b) annually through 2027, which EGP is positioned to capture via its 60:40 joint venture with Kum Fatt Engineering (CIDB Grade G7 accreditation).
Indonesia's PLN capex of SGD2.8b-3.0b annually through 2034 offers longer-term upside.
Net cash position of SGD57m (35% of market cap) as of end-2026 with zero debt provides downside protection and strategic flexibility for regional M&A and geographic expansion without dilution.
|
 See also: Aedge’s S$3.5 M Placement: Another Sign Funds Are Looking Beyond the Blue Chips |