|
Addvalue Technologies operates in highly technical and compex fields that can be difficult for the general investor to follow.
|
Jarick's latest report dated 4 Sept, still with the lofty target of 34 cents, needs deciphering for the general reader.
In plain English, it is saying Addvalue is entering a rapid growth phase driven by space communications and defence/anti-drone technology.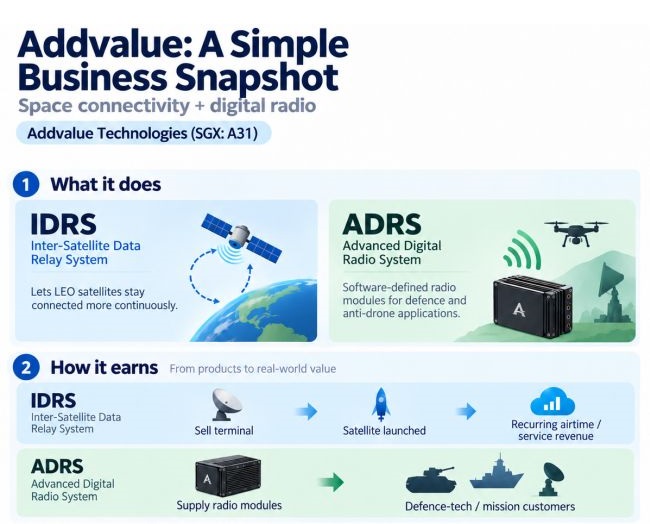
| Report’s message can be simplified to ... |
-
Orders are coming in faster and getting bigger. Addvalue recently won US$5m of new orders: US$2.8m for its satellite IDRS system and US$2.2m for its Advanced Digital Radio System (ADRS). Its order book stands at US$20.2m.
(IDRS is Addvalue’s core space technology. A small terminal is installed on a low-earth-orbit satellite. Instead of waiting until that satellite passes over a ground station to send data, IDRS lets it communicate via another satellite network, giving it much more continuous contact with operators on Earth). -
IDRS could become increasingly recurring revenue. Addvalue first sells communications terminals that go on satellites.
Once those satellites are launched, Addvalue can earn ongoing airtime/service revenue. Maybank expects this recurring income to grow as more satellites enter orbit. -
Viasat could open the US government market. Viasat, a major US satellite communications company, plans to package Addvalue's IDRS into its HaloNet service for US government customers and suppliers.
Why top pick  "Besides AI, Addvalue is benefiting from 2 of the most exciting and highest growth themes in the investment world: drones and space. It thus ranks as one of our Top Picks in the small-cap tech space."
-- Jarick Seet, analystMaybank thinks this could eventually expose Addvalue to long-duration programmes involving organisations such as NASA and create repeat orders.
-
The defence/anti-drone business is becoming important too. The US$2.2m ADRS order includes repeat purchases of Addvalue's software-defined radio products by defence-tech customers.
(ADRS is Addvalue’s other major growth business. It provides advanced radio-communication technology used in applications including defence and anti-drone systems).
Maybank expects demand for anti-drone systems to lead to larger, possibly multi-year contracts. -
Maybank expects profits to grow much faster than sales:
FYE Mar (US$ m)
FY25A
FY26A
FY27E
FY28E
FY29E
Revenue
16
25
33
45
59
Core net profit
2
5
8
13
18
Core P/E (x)
9.9
47.8
67.4
43.5
30.9
Net DPS (cts)
0.0
0.0
0.0
0.0
0.0
Source: Maybank
-
The reason profits could grow faster is scale: Addvalue already enjoys gross margins of around 50%, so if sales rise strongly, more of the additional revenue should fall through to profit.
Maybank forecasts net margins improving from about 19.5% in FY2026 to 25.5% in FY2027 and 29% in FY2028.
| What Maybank is really betting on |
The analyst is effectively saying:
Addvalue has already proved that its technology works. The next stage is turning that technology into much larger volumes of business and recurring revenue.
Maybank sees space + drones/defence as two unusually strong growth markets and thinks Addvalue has exposure to both.
After a strong run-up in stock price, investors should know that it is trading at lofty valuations.
At S$0.193, the stock trades at 67× Maybank's FY2027 profit forecast and 44× FY2028 profit.
Maybank's S$0.34 target price is not based on Addvalue being conventionally cheap.
It values the company at a very high 30× FY2027 sales, reflecting its view that Addvalue deserves a premium technology/space-company valuation.
The growth story could disappoint if Addvalue needs too much working capital, becomes overly dependent on a few customers, suffers project or supply-chain delays, or if its older Satcom business continues shrinking faster than the newer businesses grow. So a summary of Maybank's report is:
|
 → See another outperformer:iX BIOPHARMA: Why a Rare US Emergency Declaration Matters for Its Star Product